
The BCEAO Reveals Rising Financial Inclusion in the UEMOA in 2025: Seven Key Indicators to Remember
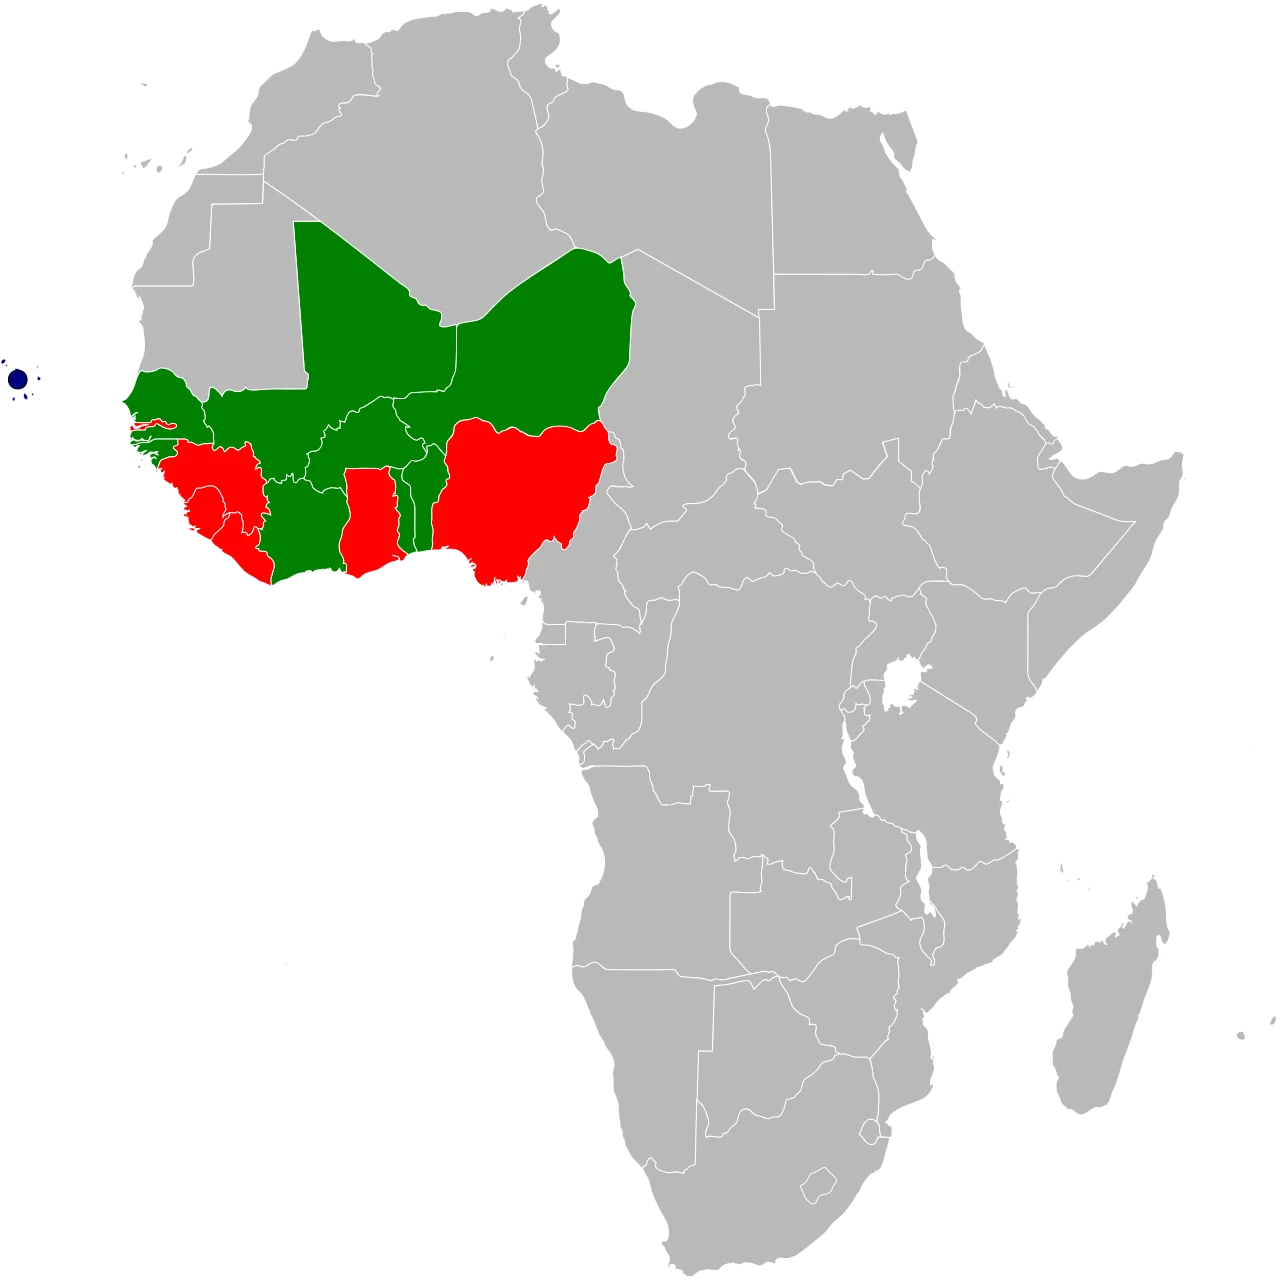
The Central Bank of West African States (BCEAO) publishes in its 2026 annual report a detailed snapshot of financial inclusion in the UEMOA for 2025. Seven indicators show significant progress, but disparities persist according to the criteria used. Here are the data and their implications for the institutions in the region.
by Lawing Tech Newsroom (4 min read)
Demographic and Geographic Indicators: Marked Progress
The 2026 annual report from the BCEAO highlights two key indicators measuring the coverage of financial services in the UEMOA: the overall demographic penetration rate of financial services (TGPSFd) and the overall geographic penetration rate of financial services (TGPSFg). In 2025, the TGPSFd saw a spectacular increase of 31 points, reaching 224 service points per 10,000 adults, according to the BCEAO. This reflects a notable improvement in access to financial services among populations, although the figure remains high due to the calculation methodology (the points do not correspond to direct percentages).
Meanwhile, the TGPSFg rose by 93 points in 2025, reaching 563 service points per 1,000 km². This indicator highlights a better territorial distribution of financial infrastructure, a crucial issue for rural areas and less densely populated UEMOA countries such as Burkina Faso or Mali.
With a 31-point increase in the TGPSFd in one year, the UEMOA confirms that financial inclusion is no longer a matter of access, but of the quality and usage of the services offered.
Banking: Uneven Progress Between Strict and Broad Measures
Two banking indicators are particularly scrutinized: the strict banking rate (TBS), which measures the number of accounts held in formal financial institutions, and the broad banking rate (TBE), including accounts in microfinance institutions and electronic money systems. This progress, though modest, confirms a trend toward the formalization of financial services.
Conversely, the TBE saw a more significant increase, rising from 47.4% to 50.6% over the same period. This gap between the two rates reveals that alternative solutions, such as electronic money accounts or microfinance services, remain dominant in accessing financial services for a large part of the population. For administrations and businesses in Benin or Senegal, this underscores the importance of strengthening partnerships with microfinance actors and fintechs to expand inclusion.
Usage and cost of services: mixed signals
This indicator, which measures the frequency of service usage by banked adults, shows more active adoption of financial tools, a positive sign for the economic stability of the region. However, this progress remains uneven among member countries, with notable gaps between capitals and rural areas.
On pricing, the report reveals mixed trends: the nominal deposit interest rate (TINd) increased by 15 basis points to reach 5.41% in 2025, while the nominal lending interest rate (TINc) decreased by 7 basis points to hit 6.69%. This dynamic could influence the strategies of local financial institutions, particularly in their ability to attract savers while maintaining accessible borrowing conditions for SMEs and households.
What this means here: opportunities and challenges for UEMOA stakeholders
For businesses and administrations in Benin and West Africa, these data points open concrete prospects. First, the rise in the TGPSFg could encourage public institutions to accelerate the deployment of financial infrastructure in underserved areas, leveraging hybrid models combining bank branches and electronic money sales points. For example, in Benin, where access to financial services remains uneven between Cotonou and northern departments, this trend could justify targeted investments in rural areas.
Next, the increase in TBE suggests that mobile payment solutions and microfinance accounts are major levers for expanding financial inclusion. Local businesses, particularly in agriculture or craft sectors, could develop partnerships with players like MoneyGram or regional fintechs to offer services tailored to their non-banked clients. For administrations, this could also serve as a basis for rethinking social aid, prioritizing disbursements through already widely adopted digital channels.
Finally, the evolution of interest rates provides a clearer framework for adjusting financing policies. National central banks, such as the Banque des États de l’Afrique de l’Ouest (BEAC) for CEMAC countries or the BCEAO for UEMOA, could use these data to refine their guidelines on interest rate regulation, balancing attractiveness for savers with accessibility for borrowers. For businesses, this could translate into more stable credit conditions, facilitating investments in key sectors like renewable energy or digital infrastructure.
Sources
- Rapport annuel sur la situation de l’inclusion financière dans l’UEMOA au titre de l’année 2025Banque Centrale des États de l’Afrique de l’Ouest (BCEAO), 26 October 2026
Prepared by Lawing Tech's technology watch from the sources cited. Our editorial charter